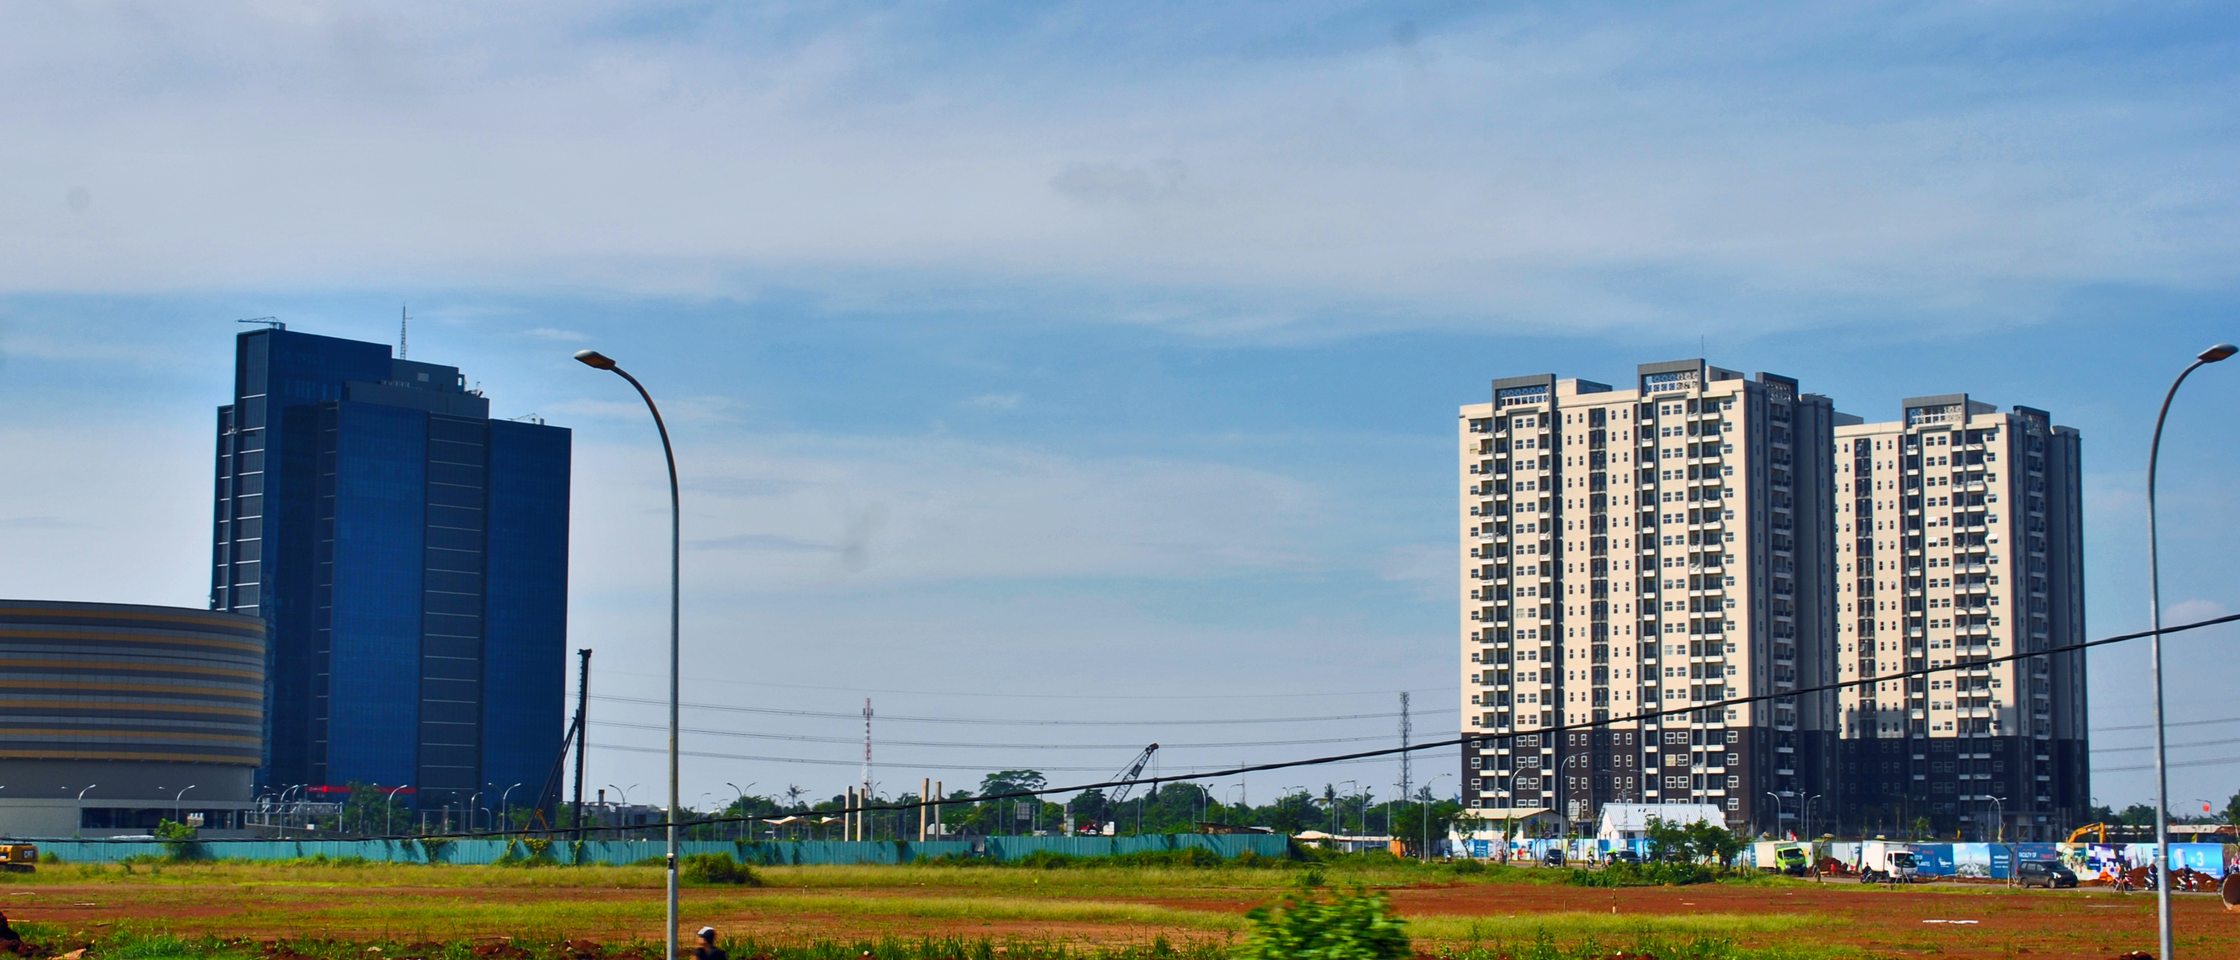
Photo: Apartment towers and open plots in Alam Sutera, Tangerang · by musnahterinjak · via Wikimedia Commons · CC BY-SA 3.0
This Month's Verdict
This is not a collapse — it is a stalemate. Sellers refuse to cut; buyers refuse to bet
Scope note: Greater Jakarta — the Jakarta special district plus its satellite cities. The condominium is the most mainstream urban housing form in Indonesia, and the property type most accessible to Chinese nationals in Jakarta. Read three numbers together: not a single new project dared a formal launch all quarter — developers only test the water with “queue registration” (NUP); prices rose 1.6% in a year, losing to 3.34% inflation, nominally up, actually down; launched projects sit at a 94.4% cumulative sell-through, but projects under construction are only 57.7% pre-sold. Finished homes sell, paper homes don't. Buyers only trust what they can see and touch. And of the homes already sold, one in three sits vacant (33.9%): buy to live in, and this is a buyer's market — take your time and negotiate hard; buy to rent out, and redo the math first.
Three Numbers
0 launches
So what: not a single new project dared a formal launch all quarter. Developers collectively “stopped opening”, only collecting small NUP intention deposits to test the water; if registrations fall short of threshold, no launch. Supply frozen.
Source: Cushman & Wakefield, Greater Jakarta Condominium MarketBeat Q2 2026
94.4% vs 57.7%
Counter-evidence: launched finished homes carry a 94.4% cumulative sell-through — finished homes are indeed selling, the problem is not here. But projects under construction are only 57.7% pre-sold, fewer than six of ten. Buyers will not pay full price for paper — a collective vote of no confidence in the “off-plan” business model.
So what: 33.9% of sold units are vacant. Of the homes sold years ago, one in three sits empty. For owner-occupiers, this is a buyer's market: pick slowly, negotiate hard. For rental investors, leasing competition is brutal — run the numbers at worst case first.
Macro backdrop: Indonesia 2026 GDP growth 5.2%, inflation 3.34%, central bank rate 5.75% (Bank Indonesia / BPS caliber, cited by the report). String the six numbers into one story: developers dare not launch (supply frozen), buyers dare not buy off-plan (demand frozen), yet finished homes are indeed slowly selling (94.4%), while a large share of homes sold years ago sits empty (33.9%).
Metric
Q2 2026
YoY
Plain reading
Existing stock
405,439 units
+0.3%
The pool has basically stopped moving — nobody dares build at scale
New launches this quarter
0 units
——
Not a single new project dared a formal launch all quarter
Cumulative sell-through
94.4%
——
Launched finished homes are basically sold — the problem is not here
Pre-sales rate, under construction
57.7%
——
Of homes on paper, fewer than six in ten are sold
Vacancy rate of sold units
33.9%
——
Of sold homes, one in three sits vacant
Average selling price
Rp52,000,000 /sqm
+1.6%
Losing to 3.34% inflation — nominally up, actually down
Source: Cushman & Wakefield, Greater Jakarta Condominium MarketBeat Q2 2026.
Three tiers: CBD, Prime, Secondary
Averages lie. Jakarta condos are not one market but three completely different markets stacked together: the more central, the more resilient; the more peripheral, the flatter. Divergence is this market's only theme. Tier definitions (source-report caliber): CBD = prime business corridor; Prime = high-income family and expat districts; Secondary = all other areas.
Tier
Stock (units)
Sell-through
Pre-sales
Avg price (Rp/sqm)
Equator note
CBD core
31,639
98.0%
35.5%
64,000,000 (+2.4%)
The only place still rising. Finished homes nearly sold out, yet new launches pre-sell only a third — in the most central address, paper still will not sell
Prime
15,028
97.8%
11.6%
55,200,000 (+1.1%)
Expat and high-income local families. Pre-sales of 11.6%, the city's lowest — this tier's buyers simply do not touch off-plan
Secondary
358,772
94.0%
58.5%
36,730,000 (+0.1%)
88% of citywide stock, prices up only 0.1% a year — Jakarta condos' base market, and a base that does not rise
Citywide total
405,439
94.4%
57.7%
52,000,000 (+1.6%)
The more central, the more resilient; the more peripheral, the flatter. Divergence is this market's only theme
The price ledger: what a home costs, and whether a foreigner can buy
Convert official averages into numbers Chinese readers can feel, then set them against the foreign purchase threshold (Jakarta apartment minimum total price Rp3–5bn, calibers differ by source — a PPAT notary must confirm case by case before transacting). The threshold lands exactly on the mainstream unit range: Secondary homes are cheap, but foreigners are not qualified to buy them; core homes qualify, but you must pick a larger unit or a high floor to clear the bar. The threshold effectively herds foreign buyers toward mid-to-large units in the core — a restriction, and indirectly what keeps that niche liquid.
Tier
Per sqm (RMB)
60sqm 2BR total price
Against the foreign threshold
CBD core
~RMB 25,400/sqm
Rp3.84bn ≈ RMB ~1.52m
If the Rp5bn threshold applies — not qualified, cannot buy
Prime
~RMB 21,900/sqm
Rp3.31bn ≈ RMB ~1.31m
Borderline zone — case-by-case confirmation required
Secondary
~RMB 14,600/sqm
Rp2.20bn ≈ RMB ~0.87m
Far below threshold — foreigners cannot buy in a personal name
FX per the source report at Rp17,917/USD, RMB at ~7.1 per USD, for intuitive reference only. Threshold source: ATR/BPN Ministerial Regulation 1241/2022 and subsequent interpretations; calibers differ (Rp3–5bn); verified Sep 21, 2026.
When This Verdict Breaks
① This report relies on a single agency dataset (Cushman & Wakefield), verified as of Sep 21, 2026 — re-verify against the latest quarter before transacting. ② If the central bank starts cutting and developers restart launches at scale, the “frozen market” verdict must be revisited. ③ The 33.9% vacancy rate is the source report's caliber (sold but unoccupied/unleased units); different methodologies may produce different figures. ④ Foreign purchase thresholds exist in two calibers, Rp3bn and Rp5bn, by source; this report lists both and endorses neither — actual transactions follow PPAT notary verification, and the threshold adjusts with policy. ⑤ “Buyer's market” and the “rental-guarantee stress-test model” are advisory judgments, not report statistics. This is a business reference, not legal or investment advice.
Evidence & Action
Where supply is heading: satellite cities and South Jakarta
Only two projects delivered citywide in Q2, 1,277 units total, all in Tangerang (1,791 units delivered in H1 cumulatively):
Project
Location
Units
Note
Elevee Penthouse & Residence South Tower 1
Tangerang
280
Middle / upper-middle positioning, Q2 delivery
Elevee Penthouse & Residence South Tower 2
Tangerang
293
As above; two towers total 573 units
Creativo Bintaro
Tangerang
704
Middle positioning; the largest single-quarter delivery of Q2
Deliveries over the next three years will concentrate in Tangerang and Bekasi, with South Jakarta next — fully consistent with the signal in our retail-market report: malls are moving to satellite cities, homes are being built in satellite cities, population and consumption are both moving out. Greater Jakarta's growth story is written outside the city in its second half.
Equator's take: four implications for Chinese readers
Owner-occupiers: you pick the home now, not the other way round★★★
Zero launches, developer inventory piled up, promotions flying everywhere, thin resale liquidity — add the four together and this is the standard portrait of a buyer's market. Negotiate boldly on anything you like: price, payment rhythm, furniture package, who pays the legal fees — every line has room. The one thing to hold is title compliance (see the red lines).
Rental investors: run the numbers at worst case first★★
A 33.9% vacancy rate means brutal leasing competition (the detailed rent ledger is in our Rental Special). Test any “guaranteed 6% annual rental” promise with this model: rent 10 months a year, rent discounted 10%, minus management fees and tax — what is left? If the math fails, do not touch the project no matter how good the developer sounds. Secondary (88% of stock) rises 0.1% a year — betting on price appreciation is even less realistic.
Chinese developers: the off-plan model does not work in Indonesia★★★
A 57.7% pre-sales rate says it plainly: Indonesian buyers do not pay full price for paper. The domestic “acquire land — pre-sell to fund — roll the development” capital model breaks its chain here. Local developers' answer is NUP (queue registration): collect small intention deposits to test the water first, and do not launch if registrations fall short. This is a low-cost trial tool, and the rule this market sets for every outsider: prove demand first, then break ground.
Do not look for loopholes — the compliant path is actually clear★★★
Foreigners cannot hold freehold title (Hak Milik). Individual buyers use Hak Pakai (right-of-use, 30+20+30 years, 80 years total), or incorporate a PT PMA to hold HGB in the company's name. Nominee holding is void from the start under Indonesia's Basic Agrarian Law — the agent's “just find a local to hold it for you” is not a shortcut, it is putting your own money into someone else's pocket.
Red Lines (six operating boundaries · foreign purchase special)
01
New units onlyForeigners can only buy new homes from developers or land-right holders — not resale units. This directly defines your choice set
02
No freeholdIndividuals hold Hak Pakai (right of use, 80 years total) — not the Chinese context of “70-year title auto-renews”. Renewal requires application; losing your residency status may affect holding
03
Minimum total-price thresholdJakarta apartments: Rp3–5bn (~RMB 1.2–2m); calibers differ by source and adjust over time — a PPAT notary must confirm the current standard before signing. Below the threshold, however cheap, the home cannot be registered to you
04
Nominee holding is a high-voltage lineHolding through a local nominee to bypass the limits is void from the start by law — when things go wrong, you recover neither the payment nor the property
05
Do not miss the taxesNew-home transactions involve acquisition duty (BPHTB, ~5%) and VAT (12% on new homes, from 2025), plus annual land and building tax. Holding costs must be computed before buying (tax items verified Sep 21, 2026; confirm with PPAT and a tax advisor before signing)
06
“Rental guarantees” are marketing talkIn a market with 33.9% vacancy, a fixed-return guarantee is honored by the developer's own cash flow, not by market rents. Treat it as an option, not as interest
2-hour diagnosis
两小时诊断
Home selection, investment modeling, compliant purchase paths — bring your questions and we will run the numbers down to the specific project. The first coffee is on us.
Data note: this report is Equator Creative Consulting's Chinese-language interpretation of Cushman & Wakefield's MarketBeat: Greater Jakarta Condominium Q2 2026 (published 2026); underlying data copyright belongs to Cushman & Wakefield. Macro figures are cited by that report from Bank Indonesia and BPS. Foreign-ownership rules follow Indonesia's PP 18/2021, ATR/BPN Ministerial Regulation 1241/2022 and public legal interpretations, verified Sep 21, 2026. FX: Rp17,917/USD (source report); RMB at ~7.1 per dollar. Limitations: ① single-agency dataset; ② the 33.9% vacancy rate is the source report's caliber (sold but unoccupied/unleased units), and different methodologies may differ; ④ foreign purchase thresholds exist in Rp3bn and Rp5bn calibers by source — this report lists both and endorses neither; actual transactions follow PPAT notary verification; ⑤ “buyer's market” and the “rental-guarantee stress-test model” are advisory judgments, not report statistics. This is a business reference, not legal or investment advice.