Equator ObservatoryEquator Creative Consulting
Greater Jakarta Market Special · 2026.09
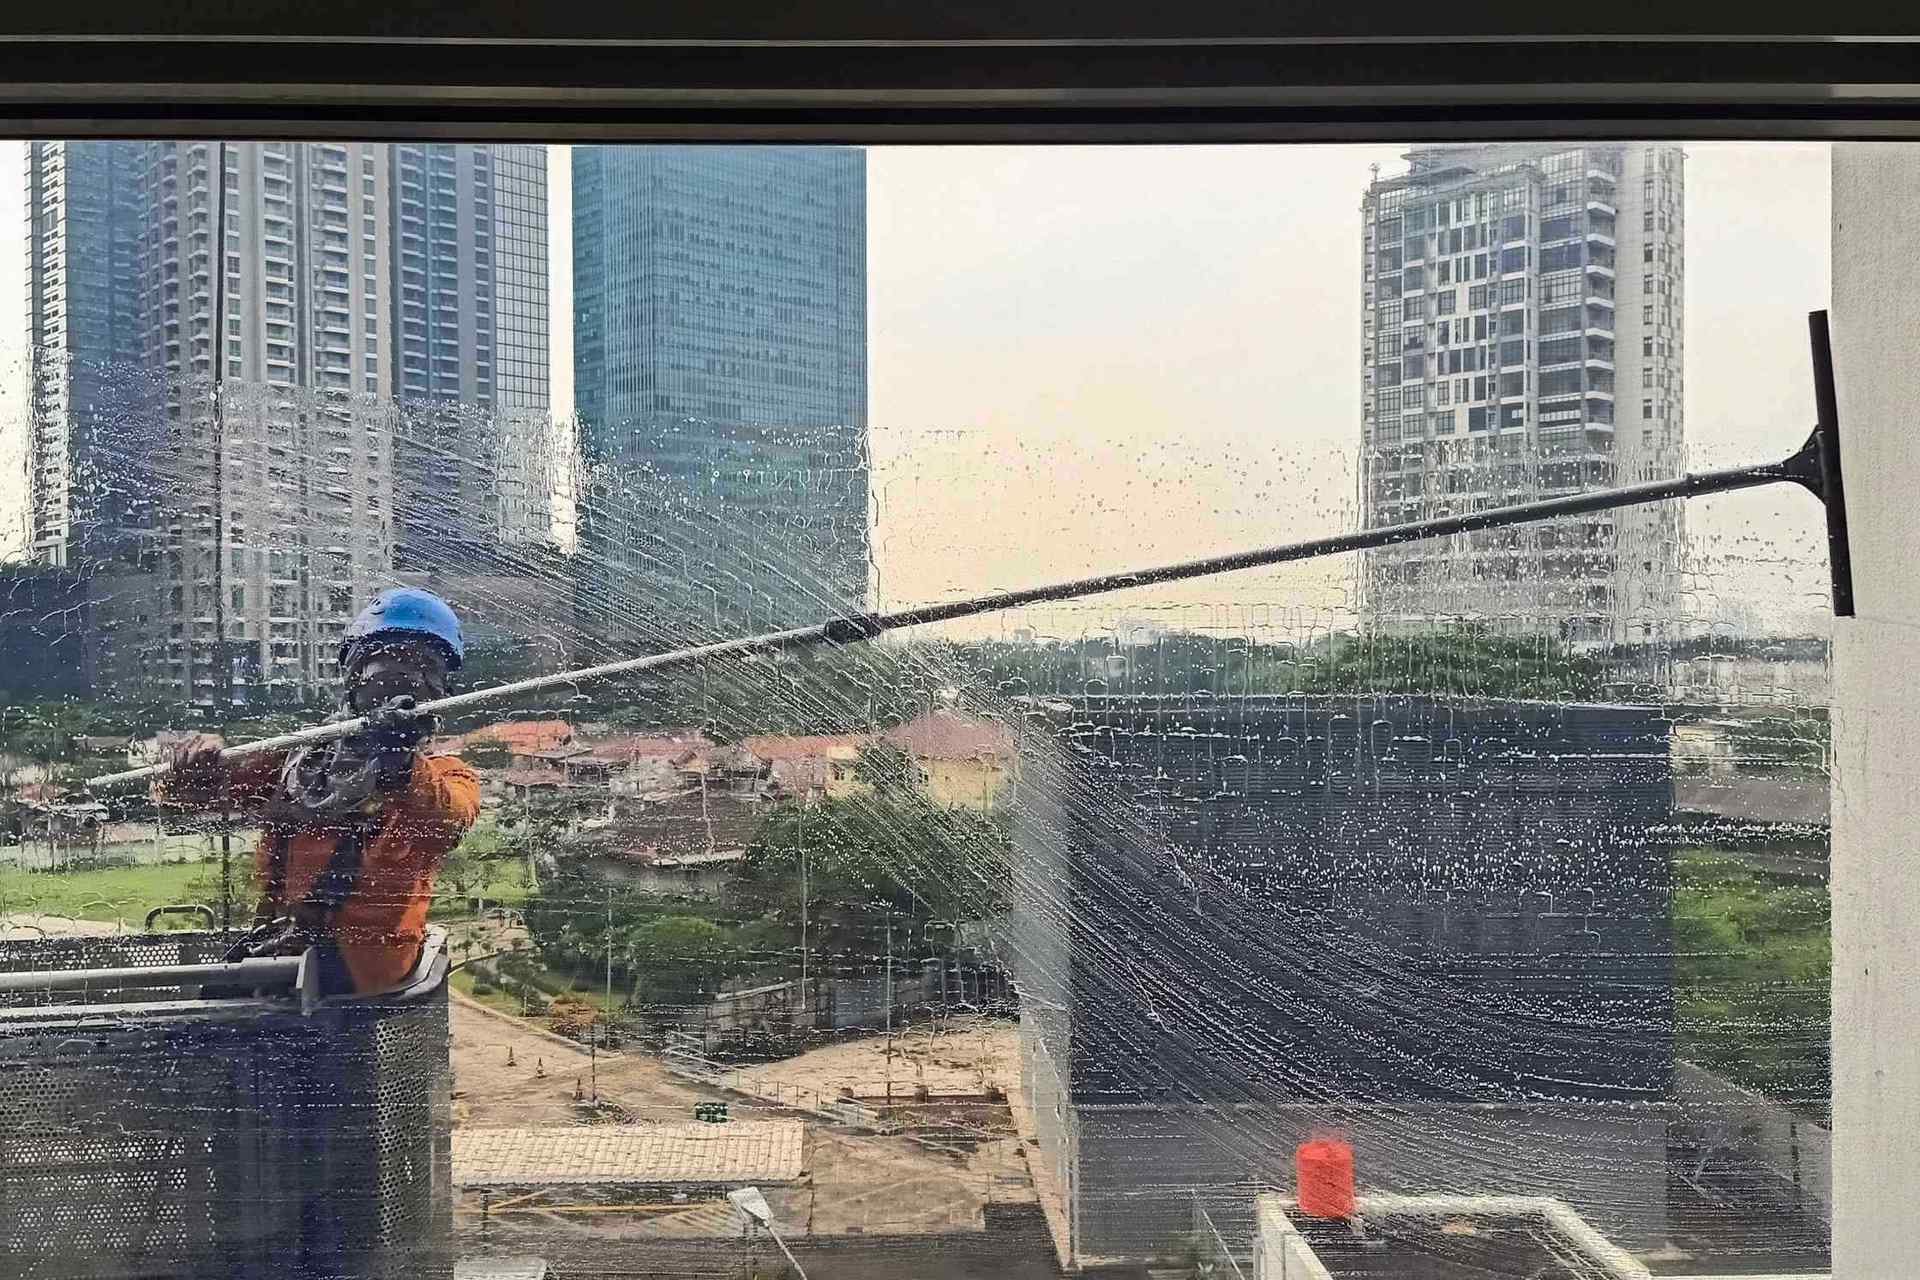
Photo: Herusutimbul / Wikimedia Commons, facade-cleaning work on a Jakarta high-rise (2021); cropped and resized, CC BY-SA 4.0 ·
source and attribution ·
licence. The image illustrates existing-building work and does not depict a project listed below.
2026 Q2 · Market Signals & Project Leads
Greater Jakarta Construction Opportunities: Industrial, Data Centres & Retrofit
For Chinese contractors considering Indonesia · Greater Jakarta includes Cikarang, Bekasi, Karawang, Tangerang and surrounding corridors
Executive view: break the “Jakarta construction market” into real locations and procurement routes. Prioritise industrial buildings, warehouses and data-centre support in the eastern corridor; treat follow-on systems, commissioning and retrofit in the CBD as leads; and track phased retail expansion and renovation. Investment, planned floor space and owner announcements are signals, not open tenders or orders a contractor can secure.
Report scope
This public edition removes the source document’s client name, company capability assessment and account plan for one company, and reframes the material as a screening framework for Chinese contractors generally. The project table records public announcements and market reports only. Private vendor portals, current site progress, main contracts and unpublished procurement plans were not individually checked. Before bidding, verify against written owner/main-contractor responses, tender documents and site checks.
Three verifiable market signals
91.85%
Leased warehouse occupancy in Q2 2026. It supports a resilient-demand view but does not mean every estate has new projects.
Cushman & Wakefield Jakarta MarketBeat Q2 2026 [4]
114,000 m²
C&W expects new leased warehouse supply by year-end 2026, concentrated in Bekasi, followed by Karawang and Jakarta.
Market supply forecast, not a tender list [4]
>100 ha
CBRE’s measure of data-centre operator land transactions in H1 2026; power and infrastructure readiness affect site selection.
CBRE Greater Jakarta Industrial Estate Figures Q2 2026 [3]
Greater Jakarta investment and industrial land: keep measures separate
BKPM reported Rp173.6T in realised investment in Jakarta in H1 2026. Selected sectors relevant here include Rp54.4T for transportation, warehousing and telecoms; Rp43.6T for other services, including data-centre activity; Rp14.0T for housing and offices; and Rp12.9T for construction. These are not a complete sector breakdown; no estimate is made for the unlisted balance.[1] A separate national provincial investment release gave DKI Jakarta as Rp94.9T.[8] The releases do not provide enough detail to reconcile their geographic aggregation and statistical bases. We show them as separate published measures, do not combine them, and do not treat investment as construction-contract value.
For industrial land, Colliers reported 36.74 hectares of Greater Jakarta absorption in Q2 2026; CBRE reported approximately 62 hectares for the same quarter and more than 100 hectares of data-centre operator transactions in H1.[2][3] Their sample boundaries and methods differ; the figures should not be added, averaged or presented as one definitive value. Both reports point to more selective investment and attention to the eastern corridor and data-centre demand. Contractors should check each estate, owner, power connection, permit, stage and procurement entity.
Market data is not order data
Land absorption, warehouse occupancy, planned supply and government realised investment measure different things. They cannot be converted directly into contract value, supplier qualification probability or project profit. This report does not estimate a market total or divide owner investment and planned capacity into invented construction packages.
Four work-package areas for contractors to screen
| Priority area | Potential work packages | Key gate and entry route |
|---|
| Industrial buildings and warehouse BTS | Factory/warehouse structure, floors, drainage, fire-system interfaces, estate roads, expansion and live-site works. | Verify floor specification, loading docks, fire approval, logistics flow and owner operating standards; start with structural or estate subcontract packages within existing qualifications. |
| Data centres and digital infrastructure | Civil/structural works, envelope, site drainage, equipment foundations and roads; where qualified, MEP interfaces, cooling and backup-power rooms. | Highest barrier. Check power capacity/timing, backup power, cooling water, fibre, permits, operations and security. Without data-centre references, do not lead with a full EPC bid. |
| Estate infrastructure | Roads, utilities, drainage, flood mitigation, earthworks, estate expansion and equipment bases. | Define utility relocation, interfaces, procurement responsibility, local subcontracting and permits; confirm owner budget and main-contractor procurement timing. |
| CBD office and retail retrofit | Office fit-out, MEP/energy upgrades, building renovation, mall expansion, common areas and phased occupied-site work. | Q2 data showed demand shifting toward Grade A, while Grade C had negative net take-up. Target assets with owner authority, budget and work windows; do not assume new office towers are the default growth path.[4] |
Publicly verifiable sector-level opportunity signals
| Segment | Public market signal | Potential work packages | Pre-bid verification |
|---|
| Industrial buildings and warehouses | Leased warehouse occupancy was 91.85% in Q2 2026; 114,000 m² of new leased warehouse supply is expected by year-end across the Greater Jakarta logistics corridor.[4] | BTS factory/warehouse structures, floors, docks, fire systems, utilities and estate expansion. | Supply is not an individual project or tender. Verify owner, funding, start date, main contractor, scope and vendor registration for each estate. |
| Data centres and supporting infrastructure | CBRE reported more than 100ha of data-centre operator land transactions in H1 2026; land measures from different firms should not be combined.[3] | Civil works, structure, envelope, equipment bases, drainage and access roads; MEP interfaces and commissioning where qualified. | Land transactions and planned capacity are not construction orders. Confirm power, cooling, permits, project stage, main contractor and unawarded packages. |
| Retail and office retrofit | About 61,800 m² of new retail space is expected by year-end; office take-up differs by CBD building grade.[4] | Phased mall expansion, tenant fit-out, HVAC/lift/fire upgrades, office energy retrofits and occupied-site works. | New supply and tenant moves do not establish a retrofit contract. Confirm owner authority, budget, asset condition and work window. |
| Industrial-estate infrastructure | Industrial-land absorption differs across consultant samples: 36.74ha in Colliers and about 62ha in CBRE.[2][3] | Estate roads, utilities, drainage, flood mitigation, earthworks and plant expansion. | Land absorption cannot be converted into construction value. Verify estate, quantities, permits, interfaces and procurement buyer. |
This table provides sector-level screening signals and excludes the source document’s client target-account combination. Do not describe a tender as open or an order as secured until at least two checks confirm the tender documents, main-contractor award, package scope and site status.
Turn market signals into bid-ready opportunities: five account checks
Confirm the legal entity and owner
Identify the land/project company, ultimate owner, funding source and formal procurement channel. Media announcements and investment MoUs are leads only.
Cross-check project stage
Use at least two of an owner announcement, tender document, site evidence, formal vendor channel or written RFI to confirm design, main tender, construction or commissioning status.
Define an executable package
Prepare a scope matrix and interface-responsibility table. Check civil/MEP/fire/power/cooling/IT interfaces, acceptance criteria, schedule window and local SBU/SKK requirements.
Model risk-adjusted cash needs
Include advances, progress payments, bonds, imported equipment, FX, taxes, delay damages, retention, rework and downside claims in the cash-flow model.
Run a bid red-team review
Verify source tender documents and signing entity; flag duplicate awards, opaque introduction fees, verbal “guarantees” and weak payment security. Reject false references, collusion and work started before a contract.
A 90-day execution sequence
Weeks 1–2: choose one lead and one backup segment
Screen for work packages supported by proven structural, schedule, quality, HSE, MEP or logistics-delivery experience; avoid generic company promotion.
Weeks 2–4: map local qualification gaps
Map work scope to current KBLI/SBU/SKK and screen partners who add local delivery, technical management and supply-chain capacity.
Weeks 3–6: validate ten owner/estate accounts
Across Cikarang–Bekasi–Karawang and CBD retrofit leads, verify the owner, procurement channel, main contractor, planned package and vendor registration.
Weeks 4–8: build benchmark bids and cash models
Model local labour/materials, import taxes, floors, waterproofing/fire systems, schedule, bonds, delays and rework for a typical warehouse or data-centre package.
Weeks 8–12: advance only evidence-backed leads
Use bid resources only where owner, scope, qualification route and payment protection are clear. Keep the rest in a watchlist with a dated next-check.
Six red lines
01Do not treat an investment release as a tenderRequire evidence of budget, buyer and timing.
02Do not treat 360MW as contract valuePlanned capacity is not subcontract quantity.
03Do not assume core packages remain openVerify awards and current stage project by project.
04Do not skip data-centre prerequisitesCheck power, cooling water, permits and interfaces first.
05Do not mobilise unsecured working capitalModel peak cash use and collection risk before pricing.
06Do not bypass local qualificationsKeep entity, licence, personnel and site responsibility aligned.
Primary sources
Scope and disclaimer
This report combines government statistics, property-research data and company announcements for market screening. It is not tender information, a project commitment, legal advice or investment advice. Forecasts and project announcements require follow-up; before pricing or bidding, independently verify owner authority, package status, qualifications, quantities and contract terms.
From Market Insight to Your Project Decision
Indonesia project-opportunity screening
Market leads · packages · qualifications and cash flow
Bring the target location, work scope, owner lead and current qualifications to map priorities and open checks.
See & Book the Diagnostic →Join the Equator Observer Circle
Indonesia projects & industry updates
Get updates on Indonesia projects and industry research.
See contact detailsYour Take
PT EQUATOR CREATIVE CONSULTINGJAKARTA · www.equatorcreative.com