Equator ObservatoryEquator Creative Consulting
Food & Beverage · 2026.10
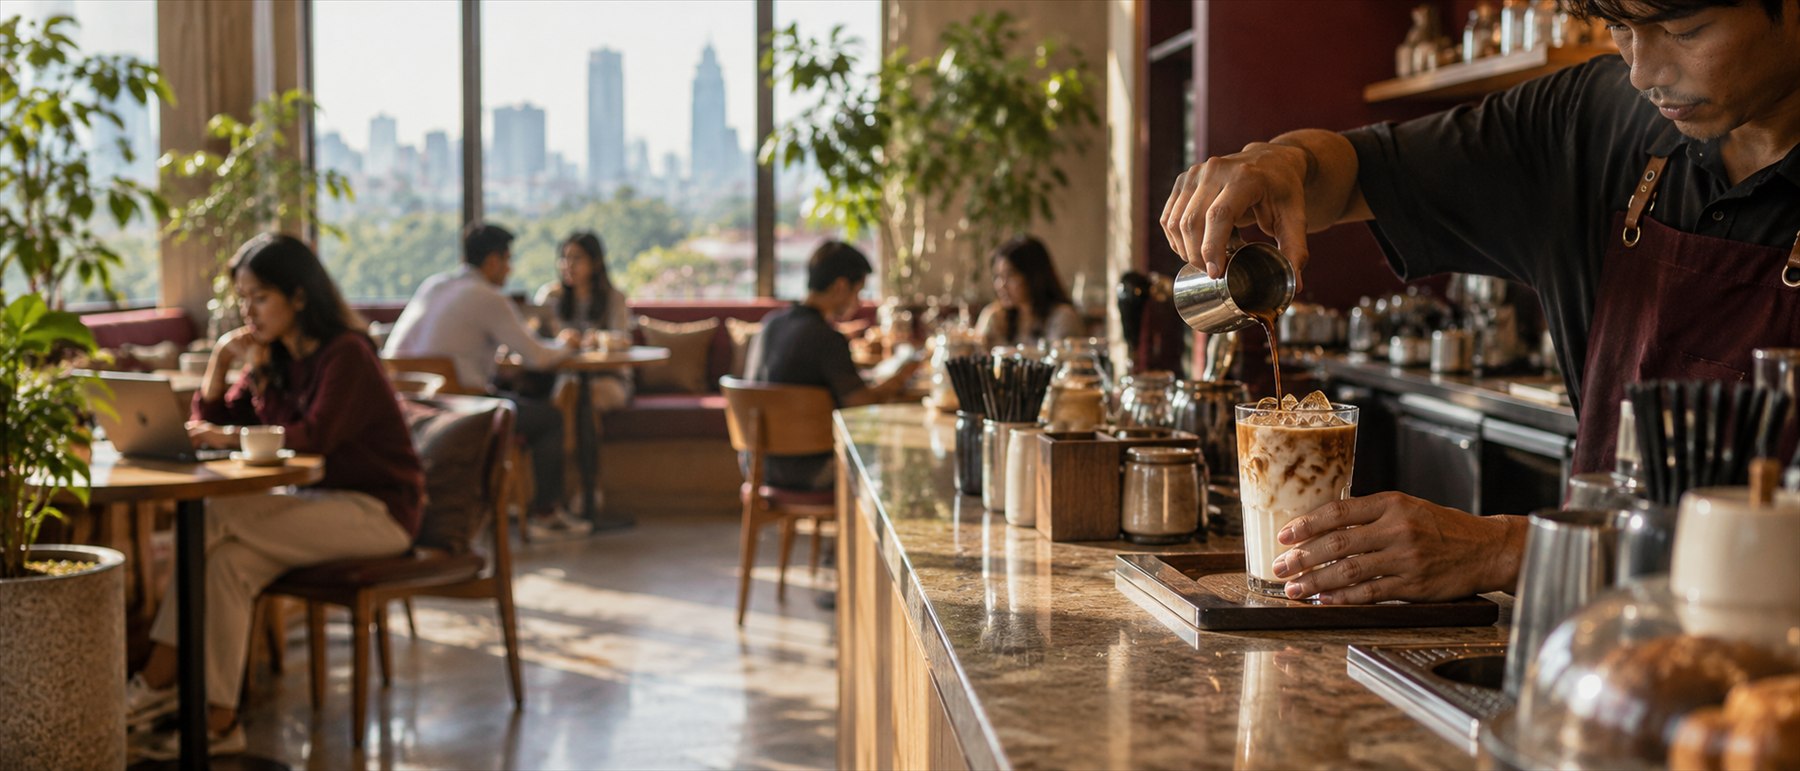
AI-generated cafe concept image for market context; it does not depict an actual Indonesian venue or brand.
2026 · Market structure, consumer occasions and chain operations
Indonesia Coffee-Chain Market and Consumer Patterns Start with occasions, then choose brands and cities
A general framework for coffee brands and operators assessing Indonesia
Executive view: Do not combine national coffee consumption, freshly prepared chains, brand outlet counts and market shares into one market. Map substitutes by occasion and price point, then test product repeat purchase, location quality and store cash returns in one city and format. Expand to comparable districts only after the pilot meets pre-set targets.
Scope and data limits
This analysis reviews the available market context. It contains no source, date, sample size or sampling method for the consumer-survey statements, and no method for the regional sales split. To avoid presenting unverified figures as fact, those statements have been reframed as questions to test and the unsourced regional percentages have been removed. Brands are illustrative examples, not a market ranking, sales-share estimate or assessment of current outlet performance.
1. Separate consumer occasions before mapping competition
| Format | Need being served | Competitive factors |
|---|
| Instant coffee at home or work | Low price, easy access, no waiting | Cost and habit; fresh-made chains should not compete on the same price logic alone |
| Street vendors and mobile carts | Quick, affordable coffee on a commute | Location and speed; a substitute for frequent everyday occasions |
| Local takeaway chains | Consistent taste, convenient ordering and small daily purchases | Coverage, local menus, loyalty and promotions, operating efficiency |
| Dine-in and experience-led cafes | Socialising, work, leisure and space | Brand atmosphere, seating, food pairings and reasons to stay |
| Independent specialty cafes | Origin, roasting, manual brewing and community | Expertise and local community; smaller scale with a clear point of difference |
Brand position varies by format, city and price point
| Illustrative brands or competitive tiers | Illustrative position | Operating questions |
|---|
| Kopi Kenangan | Mass-market local takeaway chain | Local flavour recognition, convenience, locations and store efficiency |
| Janji Jiwa | Mass-market takeaway and franchise expansion | Consistency, franchise support and regional execution |
| Fore Coffee | Affordable mid-market experience | Digital operations, menu innovation, rent and promotion discipline |
| Starbucks and other international brands | Brand experience and dine-in occasions | Malls and business districts, seating experience and price competition |
| Tuku, Point Coffee, Tomoro and independents | Segment, channel or regional competition | Community ties, channel fit, local density and product distinction |
These qualitative categories are examples for discussion. A brand may span adjacent price bands depending on city, format, average spend and promotions. Outlet counts do not establish sales share. Compare brands within the same city, target group, format, spend, throughput and trade area.
2. Five operating characteristics to account for
01
Origin does not eliminate supply volatility
Indonesia has Robusta and Arabica origins, but farming, processing, roasting, exports and urban consumption are not one simple chain. Local sourcing does not automatically mean low or stable costs.
Check grade, seasonality, logistics and alternative supply
02
Instant and low-price fresh coffee set a price anchor
Consumers can substitute home instant coffee or street coffee. A chain premium should correspond to taste consistency, convenience, trust or an experience.
Set a clear entry product and promotion limits
03
Local flavours can lower trial barriers
Kopi Susu and palm-sugar milk coffee are test directions; sweetness, ice, milk base and strength still need validation by city and customer segment.
Validate menu choices with trial and repeat purchase
04
Takeaway efficiency and dine-in experience are different models
Commuters and office workers value distance and pickup speed; social, leisure and work occasions value seating, atmosphere and food.
Model space, staffing, rent and productivity separately
05
Growth must show up in store cash returns
Rent, labour, ingredients, platform discounts and new-store ramp-up all affect store economics. Track mature-store contribution, same-store sales and cash payback.
Measure incremental repeat visits after promotions, not orders alone
3. Consumer acceptance: turn unsourced survey claims into test questions
Survey documentation unavailable
Statements about weekly out-of-home coffee consumption and rising frequency lack a survey name, date, sample size, geography and questionnaire. This page does not present those statements as findings about Indonesian consumers overall. They can guide follow-up research: How often does the target group buy coffee outside the home? Is it for convenience, taste, socialising, work or trial? Do customers repeat with the same chain?
+
Potential purchase drivers
Understandable products, availability, consistent taste, familiar local milk coffee, mobile ordering or loyalty offers, and social or temporary work space.
Cross-check interviews, orders and loyalty data
−
Potential repeat-purchase barriers
Price sensitivity, low-cost substitutes, commute patterns, queues, delivery experience and flavour fatigue.
Weekly coffee drinking is not weekly repeat at one chain
✓
Product variables to test
Core milk coffee, no- or low-sugar choices, local sweeteners, strength, ice and non-coffee drinks.
Find a few products customers will buy repeatedly
4. Choose regions by trade-area conditions, not national percentages
Regional sales split has no cited basis
A regional sales split is not accompanied by a traceable source, period or calculation method. The preview does not present such proportions as market-share claims. The qualitative regional observations below should be tested against traffic, rent, competition and store-level data in the target city.
01
Greater Jakarta: scale and competition
Office districts, commute nodes, malls, universities and new housing create different occasions. Model CBD, mall, neighbourhood and transit locations separately rather than treating Jakarta as one trade area.
02
Other Java cities: local demand patterns
Bandung, Surabaya, Semarang, Yogyakarta and Malang combine education, jobs, commerce and leisure differently. Adapt format to local rent, average spend and independent-cafe culture.
03
Outside Java: start with regional nodes
Medan, Makassar and Denpasar/Bali may be regional or visitor hubs. Proximity to coffee origins does not guarantee chain sales; check traffic, retail concentration, seasonality and logistics.
Trade-area conditions to verify
Population and commute density, concentration of offices, universities and retail, delivery access, purchase frequency and the ability to reach the same target group repeatedly. Translate these into specific streets and sites before choosing a format and investment cap.
5. Market entry and expansion: five validation gates
Customer gate: decide whom to serve
Choose everyday mass-market buyers, office commuters, students, families or specialty enthusiasts; “everyone who drinks coffee” is not a target segment.
Product gate: test local repeat purchase
Use a focused menu to test sweetness, ice, milk base, strength, cup size and non-coffee options; record trial conversion and repeat purchase.
Location gate: match city, trade area and format
Compare all-day traffic, rent, competitors, delivery radius and operating hours across offices, campuses, malls, neighbourhoods and transit points.
Economics gate: model mature-store cash returns
Include rent, labour, ingredients, platform commissions and discounts, fit-out depreciation, waste, ramp-up and FX; set payback and stop-loss limits in advance.
Replication gate: expand only to comparable trade areas
Replicate only after the pilot meets targets across weeks, dayparts and promotion conditions.
6. Four operating red lines
Editorial synthesis of operating recommendations.
01Do not treat Indonesia as one trade areaValidate occasions, customers, rent and competition at the city and site level.
02Do not infer brand share from outlet countsCoverage, sales and store profitability are different measures.
03Do not roll out nationally before proving one store modelValidate one city and format, then replicate in comparable areas.
04Do not mistake discounted orders for stable repeat purchaseInclude incremental demand, margin, platform fees and cash payback.
Turn consumer occasions into a testable store model
Indonesia consumer and retail research
Customer validation · Site assessment · Store economics
Structure interviews, competitor checks and operating assumptions around a target city and format.
See & Book the Diagnostic →Equator Observatory
Indonesia projects & industry updates
Explore market, project and industry research on Indonesia.
Contact detailsQuick poll
Your choice is stored only in this browser. It is not synced across devices and does not represent all readers.
PT EQUATOR CREATIVE CONSULTINGJAKARTA · www.equatorcreative.com